Mortgage Protection Insurance Strategies
Mortgage Protection Insurance Strategies
Mortgage protection strategies pair term life insurance with your home loan's balance and payoff timeline, so your beneficiaries can clear the debt instead of losing the property. Homeowners in Fairfax County, Loudoun County, and the DC Metro area often choose simplified issue policies, which skip the medical exam and speed approval for families needing coverage before closing.
Key Takeaways
- Mortgage protection life insurance covers your home loan if you pass away or become permanently disabled.
- Homeowners receive mortgage protection offers from lenders, mail, and insurance agents with varying coverage options available.
- Life insurance designed for mortgage protection ensures your family retains home ownership without financial burden after loss.
- Multiple mortgage insurance forms exist, requiring homeowners to compare options for adequate protection and affordability.
What Happens To Your Mortgage If You Die?
Lenders don't forgive the balance just because a homeowner has passed away. The mortgage debt transfers to the estate or surviving spouse, and payments still come due each month. Without a plan in place, grieving families face a brutal choice: keep scraping together payments or sell the home they've worked so hard to keep.
That's the gap mortgage protection insurance exists to close. This kind of coverage steps in if a homeowner or their spouse dies prematurely, or even becomes permanently disabled and can't earn an income. The goal is simple: making sure loved ones can stay in the home they love, even if the mortgage isn't fully paid off yet.
Families in Sterling, Loudoun County, Fairfax County, and across the DC Metro area often layer this protection alongside other needs. Funeral costs and end-of-life expenses add real financial pressure during an already painful stretch. Many households pair mortgage-focused coverage with a plan for those immediate costs too. That way, healing stays the focus instead of finances.
Does the mortgage get paid off automatically when you die?
No automatic payoff exists through the mortgage itself. A death benefit from life insurance for mortgage protection, or a standard term life mortgage protection policy, is what actually clears or offsets the balance. Without a policy in place, survivors inherit the payments along with the grief.
Who is responsible for mortgage payments after a homeowner's death?
Responsibility typically falls to the estate or the surviving spouse listed on the loan. Missed payments still risk foreclosure, regardless of the circumstances. Local guidance based in Sterling, VA, helps Northern Virginia families structure coverage before that risk becomes reality.
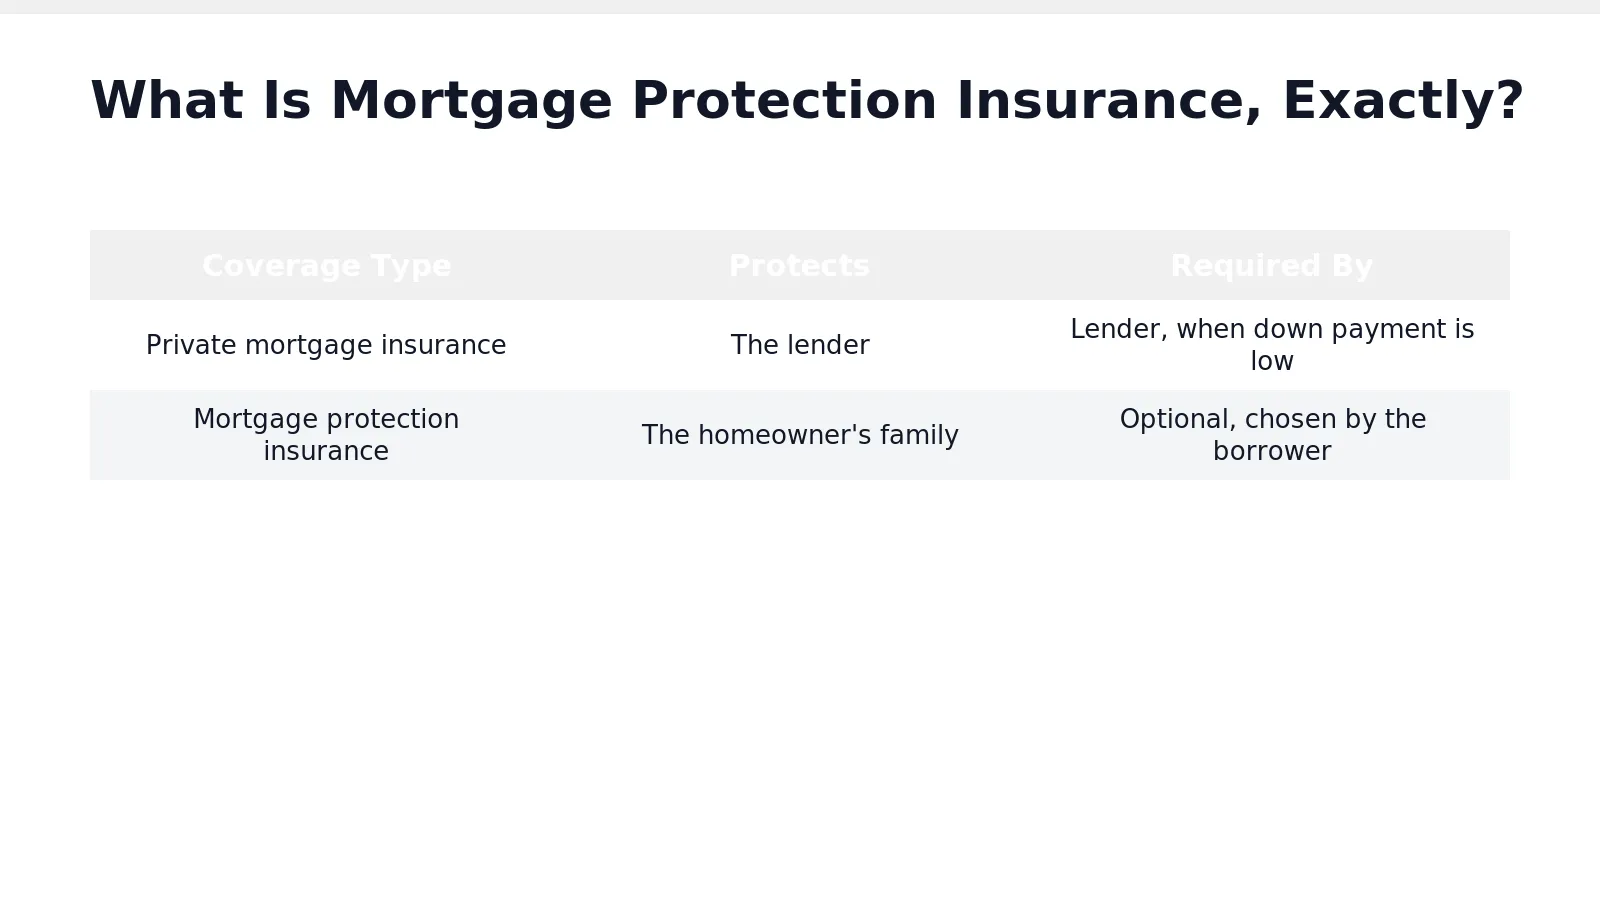
What Is Mortgage Protection Insurance, Exactly?
Mortgage insurance splits into two distinct categories, and confusing them leads homeowners toward the wrong protection entirely. One type shields a lender's investment; the other shields a family's future in the home they've built together.
The first category, private mortgage insurance, kicks in when a down payment falls short of a lender's required threshold. Lenders require this coverage as a condition of the loan itself. It has nothing to do with a homeowner's death or disability. It protects the bank's financial exposure if the loan defaults.
The second category is what most Northern Virginia homeowners actually mean when they ask about protecting their mortgage: mortgage protection insurance. This type is life insurance for a mortgage, paying out to loved ones rather than a lending institution. Families in Fairfax, Loudoun, Arlington, and across the DC Metro area turn to this coverage specifically. A surviving spouse or children can stay in the home instead of facing foreclosure.
Who benefits most from this type of coverage?
Homeowners with health conditions that complicate traditional underwriting often find simplified issue policies particularly useful. Because certain health issues create hurdles for standard applications, these streamlined options widen access to meaningful protection without abandoning the core goal — keeping the family in the home.
VIP Insures guides clients through the mechanics of coverage. How policies work, what benefits apply, eligibility rules, and how term life mortgage protection stacks up against other life insurance structures.
How Does Term Life Mortgage Protection Work?
A term policy pays a death benefit to beneficiaries if the policyholder dies during the coverage period, giving surviving family members funds to pay off the remaining mortgage balance. Term life mortgage protection works alongside a home loan rather than being tied directly to it. Families keep control over how the payout gets used. That flexibility matters for homeowners across Northern Virginia and the DC Metro area. Mortgage balances can represent a household's largest financial obligation.
Families searching for mortgage protection insurance often want something simple. Many term options built for this purpose appeal to households looking for dependable coverage without a drawn-out application process. Speed matters when a family just closed on a home and wants protection in place quickly.
Do These Policies Require a Medical Exam?
Often, no. Many streamlined term products involve minimal medical underwriting, and applicants frequently skip the physical exam altogether. Approvals move faster as a result, which suits homeowners juggling moving timelines, new mortgage payments, and other early-homeownership costs.
What If a Homeowner Wants Coverage That Lasts Longer Than a Term?
Term isn't the only path toward life insurance for mortgage protection. Homeowners who prefer permanent coverage can choose whole life insurance instead, and the differences are worth weighing:
Whole life carries fixed premiums and builds cash value that grows into a lasting asset for loved ones.
Choosing between term and permanent coverage isn't always straightforward. VIP Insures runs with a small, two-person team, and that size keeps guidance personal rather than automated. Homeowners get one-on-one help comparing term against permanent options, based on their mortgage terms, budget, and family goals.
Which Coverage Fits Your Northern Virginia Home?
Three factors usually decide the right fit: age, health, and how the mortgage connects to a business. Northern Virginia families come in a lot of different shapes. The right mortgage protection insurance plan rarely looks the same for two households on the same street.
Age and health history matter most for homeowners worried about qualifying at all. Those between 45 and 85 who fear a health condition might disqualify them can still access guaranteed issue coverage. No medical exam is required, and approval is guaranteed regardless of health history. That alone removes one of the biggest barriers families face when shopping for life insurance for mortgage protection later in life.
What if a client owns a business and a home?
Business owners carrying a mortgage often need protection on two fronts at once. Key Person insurance and Buy-Sell funding safeguard the business itself, while Final Expense coverage protects the family and the home. Pairing these tools means a single unexpected loss doesn't put both the business and the household at risk.
How does VIP Insures help pick between options?
Every client's situation gets a real review, not a one-size-fits-all pitch. VIP Insures walks through eligibility rules, compares benefits across policy types, and explains how each option fits the client's specific mortgage and family goals.
A few homeowner scenarios worth flagging:
- New buyers who drained savings on a down payment — extra coverage gives the household breathing room to rebuild an emergency fund before life throws a curveball.
- Older homeowners near retirement — guaranteed issue options remove medical exam worries entirely.
- Self-employed homeowners — combining business and personal coverage closes gaps a standard term life mortgage protection policy might miss.
Matching coverage to circumstance, rather than chasing the cheapest premium, keeps a Northern Virginia family's home genuinely protected.
How Do You Get Started Protecting Your Family?
Getting started begins with an honest look at savings, income, and what the mortgage payment would mean without a second paycheck. Families who used their savings for a down payment carry extra risk worth addressing. That cushion took time to build, and rebuilding it after a major loss adds strain during an already hard season.
A clear starting checklist helps:
- Review how the down payment was funded — savings, gift, or loan
- Estimate monthly expenses if one income disappeared
- Compare mortgage protection insurance against existing coverage
- Ask about term life mortgage protection options tied to the loan payoff timeline
- Talk through goals with a licensed agent before choosing a policy
Why does a down payment source matter for coverage decisions?
A down payment pulled from savings leaves less of a financial buffer behind. Additional protection helps rebuild that reserve while the mortgage still gets paid on schedule. Families who financed their down payment differently may need a different coverage strategy altogether.
Is customized planning necessary, or does a standard policy work?
Every household's mortgage, income, and savings picture looks different. A home represents years of work and a future worth protecting. That's exactly why a tailored approach to life insurance for mortgage debt makes sense. Homeowners across Northern Virginia can connect with the Sterling, VA-based VIP Insures team to start building a plan suited to their situation.
FAQ
What is mortgage protection insurance?
Mortgage protection insurance is life insurance that pairs with a home loan's balance. Payoff timeline, ensuring beneficiaries clear the mortgage debt instead of losing the property.
Does a mortgage get paid off automatically when a homeowner dies?
No, lenders don't forgive the balance; the debt transfers to the estate or surviving spouse, and a life insurance death benefit is what actually clears or offsets it.
Why do Northern Virginia homeowners choose simplified issue policies?
Simplified issue policies skip the medical exam and speed approval, which helps Fairfax County, Loudoun County, and DC Metro families secure coverage before closing on their home.
Conclusion
In closing, mortgage protection life insurance gives you peace of mind knowing your family won't face financial hardship if something happens to you. The right strategy aligns your coverage with your home's value and your family's needs, ensuring they're protected during their most vulnerable time. Take the time to evaluate your situation honestly, compare your options, and choose a plan that fits your life. Your family's security is worth the conversation.
About The Author
Eunice Johnson is the founder and a Licensed Life & Health Insurance Agent at VIP Insures, a family-owned insurance agency headquartered in Sterling, Virginia. As a Licensed Insurance Agent in Virginia and a Life Insurance Specialist with over 15 years of experience, she crafts customized life insurance policies, final expense, mortgage protection, and estate legacy strategies for individuals, families, and business owners across Northern Virginia and the DC Metro area. She holds certifications in financial planning and risk management, and her no-pressure, education-first approach helps homeowners throughout Fairfax County, Loudoun County, and the DC Metro area find coverage that genuinely fits their lives.
Contact Us
Ready to talk through mortgage protection options for your home in Sterling, VA and surrounding areas? Reach out to Eunice Johnson and the VIP Insures team:
- 📞 Phone: (571) 444-8475
- ✉️ Email: [email protected]
- 📅 Consultation: Schedule a Consultation with Eunice
- 🌐 Website: VIPInsures.com