Universal Life Insurance: Flexible Premium Options for Comprehensive Protection
Universal Life Insurance: Flexible Premium Options for Comprehensive Protection
Universal life flexible premium policies empower policyholders to adjust payment amounts and timing within set limits while building tax-advantaged cash value, often offering lower costs than traditional whole life insurance. This flexibility supports families and small business owners by providing adaptable permanent coverage tailored to shifting financial circumstances. Minimal payments over extended periods can limit cash value growth, so understanding policy mechanics is crucial. VIP Insures assists Northern Virginia clients in comparing universal life options against whole life and term coverage to secure lasting protection aligned with their goals.
Key Takeaways
- Flexible premium policies enable adjustments to premium payments and death benefits within insurer-defined boundaries.
- Universal life insurance builds tax-advantaged cash value that earns interest, offering lifetime protection with growth potential.
- Insufficient premium funding can reduce cash value and increase policy lapse risk over time.
- Policyholders can increase or decrease premiums based on evolving financial situations and coverage needs.
Understanding Universal Life Insurance and Its Flexibility
Universal life insurance is a permanent life insurance type—alongside whole life and others—offering lifelong protection rather than coverage limited to a set term. For Northern Virginia families and small business owners focused on long-term financial planning, the permanence and flexibility can be highly valuable.
Universal life insurance centers on adjustable premium payments instead of fixed schedules found in whole life policies. Whole life insurance features fixed premiums and steady cash value accumulation, serving as a reliable lifelong asset. Universal life insurance allows policyholders to raise or lower payments within insurer-imposed limits, providing families more control as income and expenses fluctuate annually.
This flexibility has earned universal life the nickname flexible premium life insurance, highlighting the ability to adapt funding levels instead of being locked into fixed monthly amounts.
How Does Universal Life Differ From Whole Life Insurance?
Whole life insurance offers fixed premiums with steady and predictable cash value growth, while universal life insurance permits premium adjustments over time, providing financial flexibility that whole life does not. This adaptability often benefits families managing variable expenses like mortgages, tuition, or business cash flow during tighter financial periods.
Who Typically Chooses Universal Life Coverage?
Households and business owners with fluctuating income streams commonly consider universal life first. Families assembling a universal life policy guide generally weigh this option carefully against whole life insurance before making commitments.
VIP Insures, located in Sterling, VA, partners with Northern Virginia families to compare flexible premium universal life options alongside other permanent policies, tailoring coverage to fit each household’s budget and goals.
Mechanics of Flexible Premium Life Insurance
Flexible premium life insurance offers policyholders the ability to adjust premiums, death benefits, and cash value funding within insurer limits. Rather than following a rigid payment schedule, families and business owners can contribute more during prosperous periods and less during tighter financial cycles.
This adjustability is fundamental to universal life insurance, a permanent policy type driven by flexibility. However, underfunding for extended durations carries risks, including stagnated cash value growth and potential shrinking of the death benefit. Understanding these tradeoffs is essential before committing.
Differences Between Flexible Premium and Whole Life Policies
Whole life insurance requires fixed premiums for life, while flexible premium policies allow for adjustments in payment amounts, death benefits, and how much funds the policy’s cash value, all within insurer-defined parameters.
Determining Annual Premium Contributions
Licensed VIP Insures agents provide transparent, no-pressure guidance, helping clients evaluate funding scenarios to establish comfortable contribution levels. Operating as a small two-person team, VIP Insures offers personalized, hands-on support rather than impersonal call center experiences.
Accurately structuring payments involves ongoing monitoring and consideration of factors such as:
- Current income stability and manageable flexibility
- Long-term goals for cash value accumulation against near-term affordability
- Business cash flow cycles when funding policies through company resources
An informed universal life policy guide translates these considerations into a realistic funding plan grounded in clients' real-life financial situations rather than hypothetical models.
Types of Universal Life Insurance: Investment and Index Options
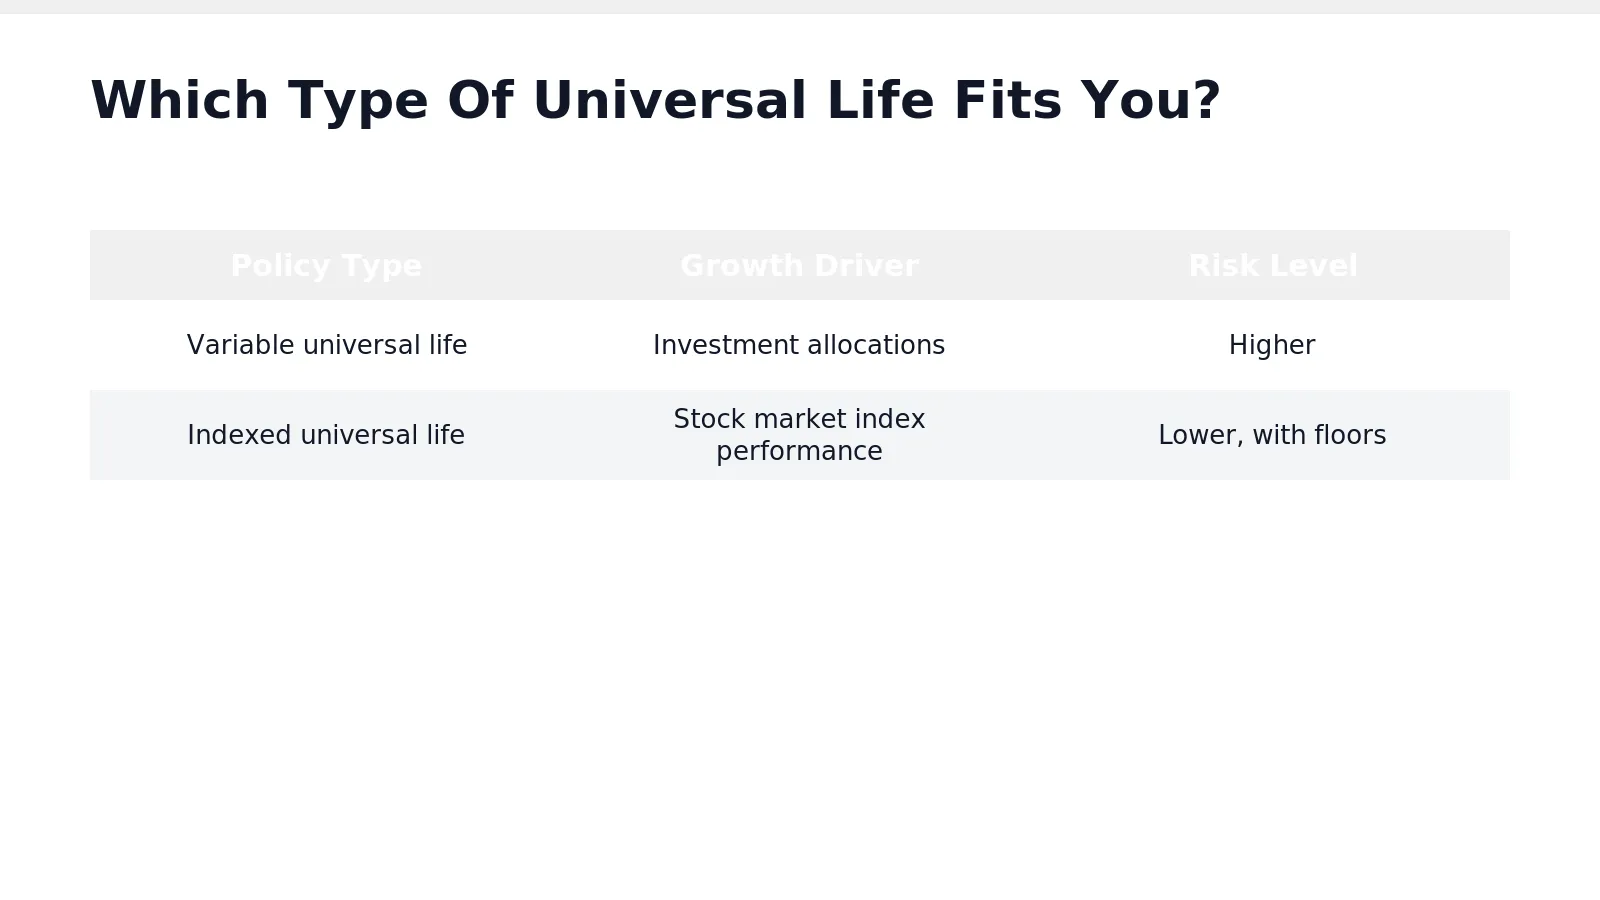
Universal life policies build cash value through two primary methods: linking growth to investment performance or to a stock market index. The appropriate choice depends on a family’s or business owner’s appetite for market risk.
Variable universal life grants policyholders control over premium allocations into various investment options, potentially enhancing cash value growth beyond standard policies. The potential for increased returns comes with the risk of investment losses reducing cash value.
Indexed universal life links cash value growth to the performance of stock market indices. Earnings rise when indices perform well but are generally protected by built-in floors that minimize downside risk—offering steadier growth potential with some exposure to market gains.
Choosing the Best Universal Life Option for Cash Value Growth
Variable universal life usually offers the highest potential cash value growth ceiling, as premiums are invested directly. Indexed universal life provides a balance by trading some upside potential for protection through downside floors. Families comfortable with market fluctuations often prefer variable policies, while those seeking steadier growth may lean toward indexed coverage.
Matching any universal life policy to a household's goals requires more than comparison charts. VIP Insures evaluates over 70 highly rated carriers to craft personalized universal life policy guides and flexible premium life insurance plans tailored to clients’ budgets and long-term objectives.
Tradeoffs and Considerations for Families and Business Owners
The flexibility of universal life insurance comes with responsibility. While families and business owners gain freedom to adjust premiums, this flexibility demands attentive management to avoid unintended cost increases or policy lapse.
Insurance costs depend on variables including age, health, coverage amount, fees, and funding strategy. These expenses commonly rise with age as cost of insurance increases, meaning a policy affordable at 35 may become significantly more expensive by age 55 if funding remains minimal.
Using a Universal Life Policy Guide for Business Protection
A well-crafted universal life policy guide assists business owners in aligning coverage with operational and personal needs. Common applications include key person insurance that protects companies from financial loss due to the unexpected death of critical employees or partners, and buy-sell agreements that provide liquidity to purchase shares of a deceased owner without financial strain. Such strategies safeguard both family livelihoods and business continuity.
Evaluating Coverage Options as a Family
Families comparing flexible premium life insurance against other permanent policies should weigh several key tradeoffs:
- Premium flexibility versus fixed, predictable payments
- Potential for cash value growth versus guaranteed accumulation
- Long-term cost increases versus locked-in pricing
- Need for funding discipline versus minimal maintenance
VIP Insures offers personalized plans spanning whole life, term, and final expense coverage, alongside business protection solutions designed to preserve a family’s financial legacy. Selecting the right structure for each household and assessing a business's risks are critical for future financial security.
Choosing the Right Universal Life Policy
Your lifestyle and willingness to engage with policy management are paramount in choosing the right plan. Flexible premium life insurance suits families and business owners who want lifetime protection with adaptable payments reflecting income variability. This option requires active monitoring to maintain desired coverage levels and cash value growth.
Ongoing engagement is essential. Policies left on autopilot with minimal consistent payments risk diminishing cash value growth and reduced death benefits. Regular review of statements and proactive management keep coverage strong and aligned with evolving needs.
Consulting an Agent Before Choosing a Policy
Engaging with a local Sterling, VA-based agent transforms an abstract universal life policy guide into a concrete, personalized plan. Families gain expert insights on premium levels and funding strategies, ensuring informed decisions tailored to their situation.
Advantages of Working with a Small Agency
VIP Insures operates as a lean two-person team, ensuring clients receive direct, timely responses without call center delays. Clients discussing premium flexibility, cash value timing, or coverage specifics speak with the same dedicated professionals managing their policies. For families considering multiple insurance options, VIP Insures helps with key questions:
- Confirm actual premium flexibility permitted by a policy
- Understand implications of underfunding on long-term cash value
- Clarify consequences of temporarily pausing payments
This direct, personalized attention makes choosing coverage simpler and less overwhelming.
Frequently Asked Questions (FAQ)
What makes universal life insurance flexible?
Policyholders can adjust premium payments, death benefits, and cash value funding within insurer-set limits, avoiding a rigid, fixed payment schedule. This flexibility is especially beneficial for families and business owners with fluctuating income.
How does universal life compare to whole life insurance?
While whole life insurance features fixed premiums and steady, predictable cash value growth, universal life allows adjustable premiums tied to funding and interest, often at a lower cost than whole life coverage.
What happens if premium payments stay too low?
Consistently minimal payments reduce cash value growth and increase the risk of policy lapse. VIP Insures, based in Sterling, VA, helps Northern Virginia clients assess these tradeoffs compared to whole life and term insurance options.
Conclusion
Universal life insurance with flexible premiums offers the adaptability life demands by allowing premium and death benefit adjustments as circumstances evolve. Whether navigating career changes, expanding families, or revising financial goals, this flexibility ensures coverage remains relevant and effective. Understanding policy mechanics empowers you to protect your loved ones without undue financial strain. Ready to determine if a flexible premium policy suits your needs? VIP Insures is here to guide you every step of the way.
Contact VIP Insures
- 📞 Phone: (571) 444-8475
- ✉️ Email: [email protected]
- 📅 Consultation: Meet with Eunice
- 🌐 Website: vipinsures.com
- 📍 Service Area: Northern Virginia, Washington DC Metro area, and nationwide