When to Update Life Insurance Vipinsures: When to Update Life Insuranc
When to Update Life Insurance Vipinsures: When to Update Life Insuranc
Major milestones such as marriage, a new baby, buying a home, or launching a business signal the need for a policy review. VIP Insures, a licensed, family-owned agency in Sterling, VA, helps Northern Virginia families compare carriers like Mutual of Omaha and New York Life to adjust coverage as life changes.
Key Takeaways
- Marriage, divorce, and birth of children trigger immediate life insurance policy review requirements.
- Loss of health coverage qualifies as a life event requiring policy updates within 60 days.
- Relocation to a new state often necessitates policy adjustments due to varying insurance regulations.
- Significant income changes, salary increases or job loss, demand reassessment of your coverage amounts and beneficiaries.
Which Life Changes Mean It's Time To Update?
Marriage, a new baby, or the loss of other coverage all signal when to update life insurance vipinsures clients rely on for peace of mind. Skipping that review leaves a growing family exposed at the exact moment protection matters most. A policy built for a single person rarely fits a household with a mortgage, a newborn, or a second income to protect.
These life events change policy vipinsures considerations generally sort into a few recognizable buckets:
- Household shifts: marriage, divorce, a new child, or a child reaching adulthood
- Loss of coverage: leaving a job, retiring, or losing eligibility through a spouse's plan
- Residence changes: relocating across county lines or out of Northern Virginia entirely
- Other triggers: income changes, starting a business, or paying off a major debt
Does buying a home count as a reason to review coverage?
Yes. A mortgage adds a long-term financial obligation that a policy written years earlier may not cover. Homeowners in Fairfax, Loudoun, or Arlington often find their existing death benefit no longer matches their debt load.
What happens if beneficiaries are never changed?
Outdated paperwork can send proceeds to an ex-spouse or an estranged relative. Reviewing and confirming an update beneficiary life insurance vipinsures clients trust helps ensure the right people receive support. Fairfax County families increasingly lean on independent, local advisors who compare multiple carriers instead of settling for one-size-fits-all coverage.
Why Does Marriage Or A New Baby Matter?
Marriage and new children rank among the clearest signals for when to update life insurance coverage. Qualifying life event guidelines specifically name having a baby or adopting a child as a household change that can trigger a need to revisit both coverage amounts and beneficiary designations. A wedding ring or a nursery doesn't just change daily routines; it changes who depends on a paycheck.
Northern Virginia families often picture life events change policy needs in terms of bigger coverage, and that instinct is correct. A growing household means more mouths to feed, a possible move to a larger home in Fairfax or Loudoun County, and new financial obligations that didn't exist before. Final expense coverage plays a quiet but important role here, too. It helps pay funeral and end-of-life costs. A young family never has to choose between grieving and scrambling for cash.
Does Having A Baby Mean Updating My Policy?
Yes. A new child is a textbook household change that calls for reviewing both coverage amounts and who's named to receive the payout. Skipping this step leaves a newborn financially unprotected if the unexpected happens.
What Type Of Policy Fits A Growing Family?
Whole life insurance often fits well because it builds cash value over time. That cash value becomes a lifelong asset, one that can be adjusted as the family's needs expand with each new milestone.
Newlyweds and new parents share one thing in common: someone new now counts on them. That's exactly why update beneficiary life insurance steps belong on every new parent's. Newlywed's to-do list, right alongside hospital bags and wedding invitations.
How Does Buying A Home Change Your Coverage?
Buying a home resets the financial math behind a life insurance policy. A move to a different ZIP code or county counts as a change-in-residence event. It's one worth pausing on to review existing coverage. New mortgage payments, property taxes, and higher monthly costs mean the old policy amount might not stretch far enough anymore.
Homeowners across Fairfax County and the wider Northern Virginia area carry distinct financial pictures. A young family in Loudoun County with a 30-year mortgage faces different risks than a longtime Arlington homeowner nearing payoff. Life events change policy needs because the math behind "how much coverage is enough" shifts every time debt, income, or dependents change.
Why does a bigger mortgage mean more coverage?
A larger loan balance raises the stakes if a primary earner passes away unexpectedly. Surviving family members still owe the bank, regardless of what happened to household income. Coverage that once felt generous can suddenly fall short, leaving loved ones to cover a mortgage on a single paycheck.
Who can help homeowners figure out the right amount?
National carriers have responded by building local advisor networks specifically for Fairfax County. Generic call-center service rarely fits a homeowner's actual situation. Mutual of Omaha Advisors, for example, operates locally in Fairfax, giving residents another carrier to compare once their housing situation changes.
Knowing when to update life insurance after a home purchase comes down to one question: would the current payout cover the new mortgage plus everyday living costs? If not, it's time to revisit the numbers, and updating beneficiary designations should happen alongside any coverage review.
When Should Business Owners Revisit Their Policy?
Business milestones, not calendar dates, should trigger a policy review. Launching a company or bringing on a partner changes what coverage actually needs to accomplish. A policy built for a solo entrepreneur rarely fits a growing team or a multi-owner partnership.
Growth often means new financial obligations that a basic policy never anticipated. Adding key person insurance or buy-sell funding protects what the business has already built, from equipment and contracts to client relationships. These tools also protect the people who depend on that income, including employees and family members tied to the company's success.
What If a Business Owner's Health Changes Later On?
Health shifts later in life don't have to shut the door on coverage. Guaranteed issue options, often available for owners between ages 45 and 85, skip the medical exam entirely. Approval comes regardless of health history, which matters for owners who delayed updating a policy and now face new health concerns.
Does This Work Like Other Insurance Enrollment Rules?
Timing matters here just as it does with health coverage enrollment periods. Major changes, like forming a business, adding a partner, or facing a health shift, work similarly to qualifying life events in other insurance contexts. Waiting too long after a change leaves gaps that a quick update could have closed.
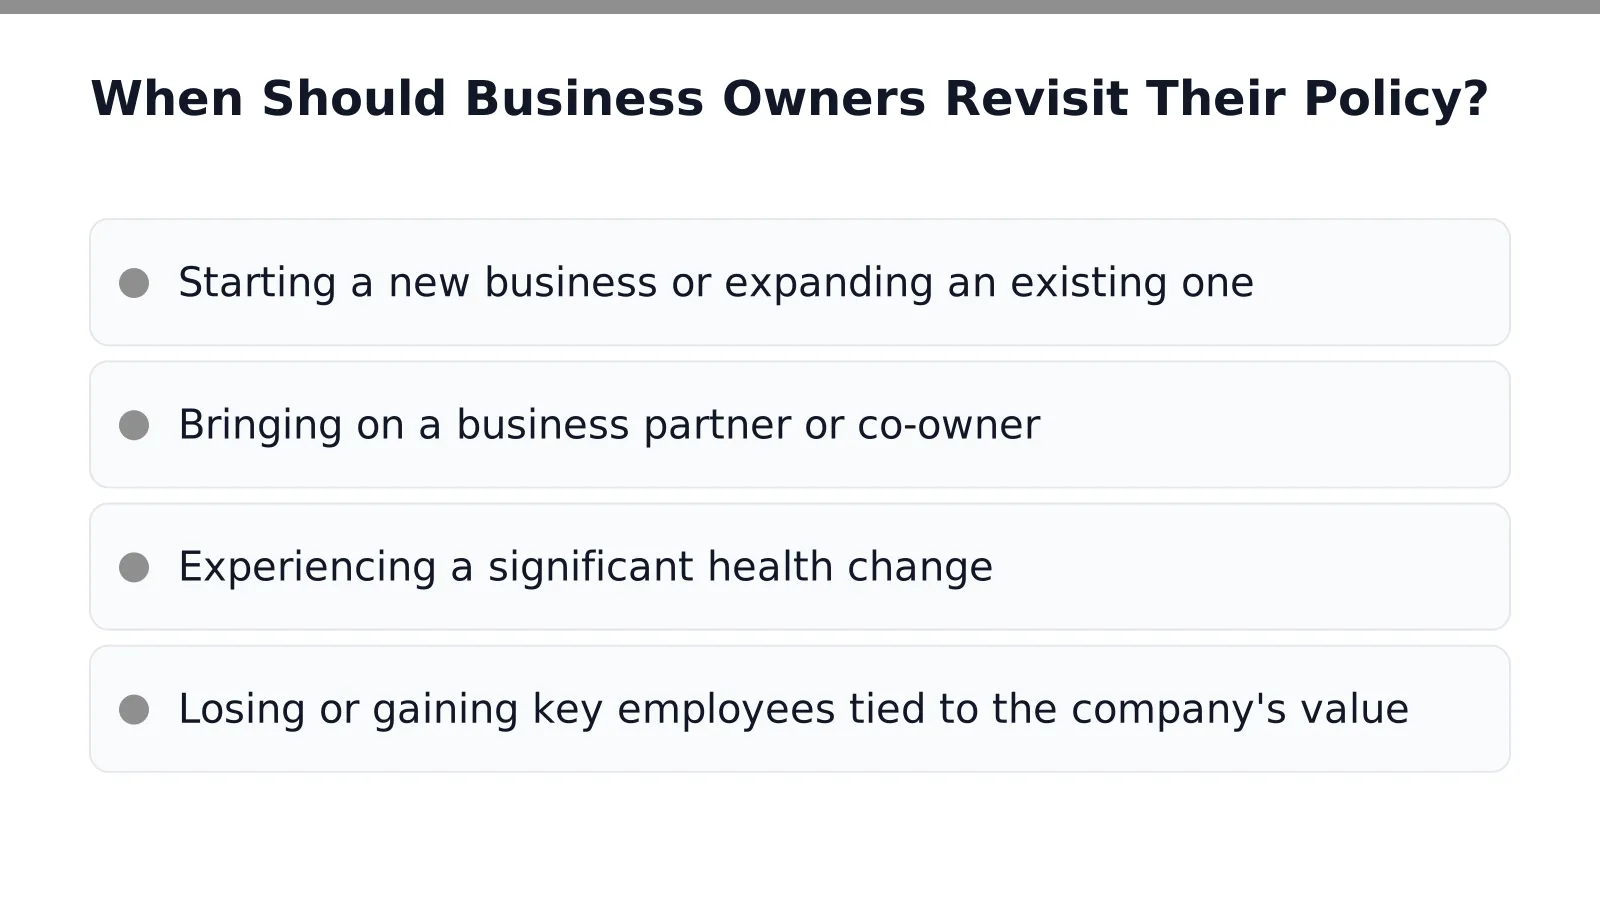
A few moments worth flagging for review:
- Starting a new business or expanding an existing one
- Bringing on a business partner or co-owner
- Experiencing a significant health change
- Losing or gaining key employees tied to the company's value
Owners working through these moments benefit from a direct conversation rather than a scripted call center experience. A small, two-person team based in Sterling, VA, reviews these situations one owner at a time, matching coverage to where the business actually stands today.
Who Should You Call To Update Beneficiaries?
A licensed agent who already knows the household's policy history is the right call, not a generic customer service line. VIP Insures operates as a licensed, family-owned agency based in Sterling, VA, built specifically to serve Northern Virginia families through personal, no-pressure conversations. That local, familiar presence matters most during stressful transitions, when families don't have the patience for automated phone trees.
A wedding, a new baby, a divorce, or the loss of a loved one all count as a qualifying life event, meaning any planned or unplanned change that affects existing coverage. These moments are exactly why reviewing life events and policy changes regularly keeps protection aligned with real life. A policy written for a single person rarely fits a growing family, a new homeowner, or a business owner adding partners.
Can a small agency really give personal service?
Yes. VIP Insures runs as a small, two-person team, which keeps conversations direct and personal rather than routed through layers of departments. That structure means families speak with someone who actually remembers their situation, not a rotating cast of representatives.
What should families ask when updating a beneficiary?
Families should confirm how the change gets processed, how long it takes, and whether any other policy details need a second look. Updating a beneficiary on a life insurance policy often reveals outdated coverage amounts or missed riders. A quick call covers both issues at once.
Because every household's needs look different, from newlyweds to multi-generational homeowners to business owners protecting partners, tailored coverage built around those specifics works far better than a one-size-fits-all plan. Families across Fairfax, Loudoun, Arlington, and the DC Metro area can reach that kind of direct, personalized guidance through VIP Insures.
FAQ
What life events signal a need to update life insurance?
Marriage, a new baby, divorce, buying a home, starting a business, loss of other coverage, relocation, and significant income changes all signal a need to review and update life insurance coverage.
Does buying a home require a life insurance review?
Yes, a mortgage adds a long-term financial obligation that an older policy may not cover. Homeowners in Fairfax, Loudoun, or Arlington often need to adjust their death benefit.
Why does it matter to update beneficiaries after a life event?
Outdated beneficiary designations can send proceeds to an ex-spouse or estranged relative, so reviewing and confirming beneficiaries helps ensure the right people receive support.
Conclusion
In closing, life's biggest moments, marriage, children, home purchases, career changes, deserve thoughtful protection. Updating your life insurance policy when these events happen ensures your loved ones stay covered through whatever comes next. Think of it as keeping your financial safety net in sync with your real life. Your family's security is worth that conversation. Reach out when life shifts and let's make sure your coverage does too.